

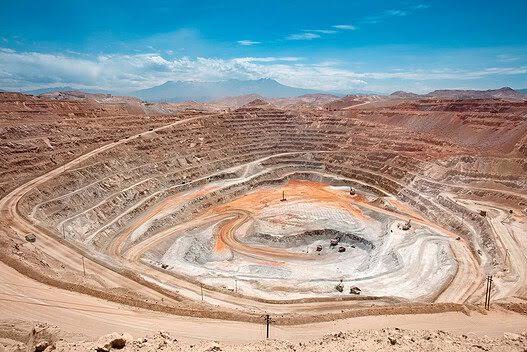
India’s natural resource companies sit at the base of almost every industry, from housing and automobiles to power transmission and electronics. Investors who study Vedanta Group Stocks often find a rare mix of zinc, aluminium, oil, power, and other businesses under one umbrella. When they check the Vedanta Share Price, they are really looking at the market’s view of that entire portfolio, not a single product line. Understanding how such a conglomerate works is the first step towards judging whether it suits your portfolio.
What Makes a Resource Conglomerate Different
A typical manufacturing company makes money by turning inputs into finished goods with a margin. A resource company makes money by extracting or processing commodities whose prices are determined by wider demand and supply, not by the company. This provides the business with a very different character. Profits can rocket when prices improve and shrink just as quickly when they soften.
In a diversified group, different divisions respond to different cycles in commodity prices. Zinc may do well while aluminium is weak, or oil may offset the softness in another metal. This spread does not guarantee risk, but it can smooth earnings compared to a company dependent on a single product.
The Strategic Importance of Domestic Resources
India imports a large chunk of its energy and several key industrial metals, pushing policymakers to promote domestic production. Mining, smelting and refining capacity that have been built up by the country support self-sufficiency, reduce the burden on the import bill and provide employment to regions where other industries are thin on the ground.
For investors, this policy backdrop is integral to understanding why government focus on infrastructure, renewables, electric mobility and defence manufacturing increases the demand for metals for years to come. Companies that have mines, refineries and smelters of their own are poised to benefit, but actual returns will depend on the execution and pricing.
Operating Scale and Cost Position
In commodity businesses, the ones with the lowest cost tend to survive downturns and thrive during upturns. Size, quality of ore, captive power, logistics and technology all play a role in costs. A smelter that has its own power supply and long-life mines is less vulnerable to fluctuations in inputs than a smaller rival that buys up from the market.
When analyzing such firms, look at unit cost over several years rather than one quarter. See if the company is able to move down the cost curve due to efficiencies, or whether the costs are rising due to aging mines, higher royalties or coal and power expenses.
Governance, Disclosure and Structure
Large groups tend to have complex ownership structures, with a parent company holding shares in listed subsidiaries. This can create value, but it can also lead to complexity. The flow of cash may be upwards in the form of dividends, and decisions made at the parent company level can impact minority shareholders in subsidiaries.
Read the shareholding pattern, related-party transactions and announcements of restructuring or demergers. Proposals to separate businesses into independent listed entities serve to unlock value, simplify analysis and let each division raise capital on its own merits. Whether they work will depend on the timing, approvals and market reception, so think of them as a possibility and not a certainty.
Environmental and Social Responsibility
Mining and metal processing tend to draw scrutiny over land use, water use, emissions and community relations. Regulators and courts in India have intervened in some sensitive projects, and compliance costs can be significant. A company that invests in cleaner technology, rehabilitation and community development reduces the risk of costly disruptions.
Investors are increasingly looking at sustainability disclosures in addition to financial statements. A single plant closure, however brief, can impact production and sentiment. Responsible practices are therefore not only ethical choices but also financial safeguards.
Weighing Opportunity Against Risk
The opportunity lies in India’s long-term appetite for metals and energy, as well as the operating leverage that comes with large fixed assets. The risk lies in fluctuations in commodity prices, regulatory shifts, debt levels and complex group structures.
A sensible approach is to avoid overweighting the sector. Cyclical stocks can deliver excellent returns, but when sold at the right phase of the cycle, they can also disappoint investors who buy them as steady compounders. Spread your investments between defensive and growth sectors, and increase exposure gradually rather than in one go.
Final Perspective
Diversified resource groups reward investors who understand cycles, costs and capital allocation. They punish those who follow headlines without regard for balance sheets. Read the annual reports, quarterly commentaries and compare the contribution of each division to profits to develop a view.
